
By Gloria Ikibah
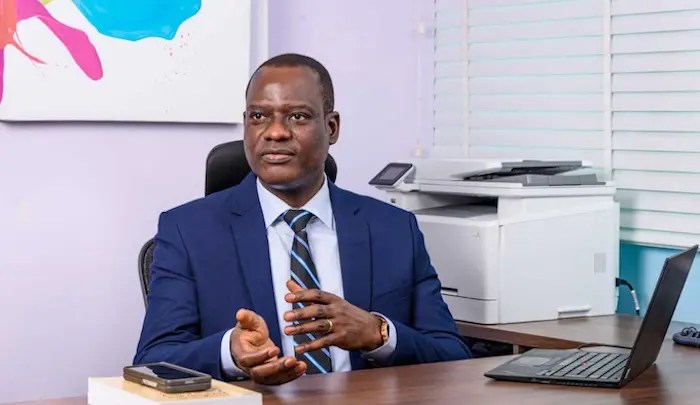
The Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, has called for greater access to affordable long-term capital to enable African countries finance infrastructure and accelerate development.
Oyedele made the call while addressing the United Nations Dialogue on Solutions to Climate Finance on the margins of the 81st Session of the United Nations General Assembly in New York. 
The minister said Africa’s development ambitions, particularly in the energy sector, continued to be held back by high financing costs, currency risks and limited access to affordable long-term funding.
He said the continent faced additional costs in accessing international capital despite its relatively low contribution to global carbon emissions.
According to Oyedele, Africa continues to bear what he described as a “prejudice premium” and “narrative cost” when seeking financing for critical infrastructure.
He also identified currency risk and what he termed “stereotype tax” as further burdens affecting African countries’ ability to raise capital for energy and other development projects.
Oyedele called for a rethink of the global approach to climate finance, urging the international community to make funding more accessible and affordable for developing countries.
He said financing arrangements should better reflect the economic and development realities of African countries, rather than impose financing conditions that make critical infrastructure projects more expensive.
The minister also called for increased investment in gas and other transition energy sources, particularly in Africa, saying such investments were necessary to expand access to reliable and affordable energy and tackle global energy poverty.
He argued that increased investment in Africa’s energy sector could also help diversify global energy supplies and reduce concentration risks, particularly amid disruptions affecting the Gulf region.
Oyedele stressed that Africa’s energy transition must take into account the continent’s substantial energy-access deficit.
He said African countries needed increased investment to meet their development requirements while pursuing a practical transition towards cleaner energy sources.
For Nigeria, the minister said the immediate priority was to implement policies and programmes capable of reducing poverty, expanding economic opportunities and accelerating the distribution of shared prosperity.
He said achieving those objectives would require stronger international cooperation and a financing framework that enabled developing countries to mobilise the capital needed to build infrastructure and improve living standards.
Oyedele’s call comes as the Federal Government continues to emphasise access to capital as a key requirement for investment, infrastructure development and economic growth. The Federal Ministry of Finance has also identified long-term financing and access to credit as important to unlocking investment in infrastructure and industry.
The minister said the international financing system must therefore do more to support developing countries in meeting their infrastructure and development needs, particularly in sectors such as energy where investment requirements remain significant.