
By Gloria Ikibah
The Federal Government has reduced the interest rate charged on late payment of taxes, with the new regime taking effect from October 1, 2026.
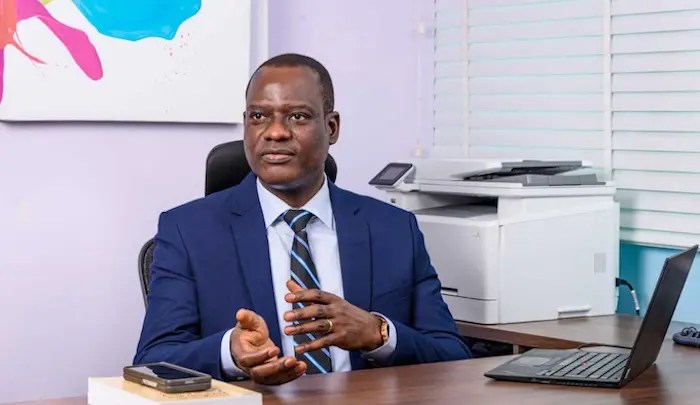
The Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, issued the Nigeria Tax Administration (Interest on Late Payment of Tax) Order, 2026, under Section 65 of the Nigeria Tax Administration Act, 2025. 
The new order applies uniformly to federal, state and FCT tax authorities and links the interest charged on late tax payments more closely to prevailing market rates.
Under the new arrangement, interest on tax payable in naira will be charged at the Central Bank of Nigeria’s Monetary Policy Rate plus one percentage point.
However, the rate will not fall below the yield on 364-day Treasury Bills, reflecting the government’s cost of funding when tax payments are delayed.
The new spread represents a reduction from the previous five percentage-point margin.
For taxes payable in foreign currency, the interest rate will be based on the Secured Overnight Financing Rate (SOFR) plus six percentage points. Where SOFR is discontinued, its official successor rate will apply.
The applicable rate will be reviewed monthly and fixed on the last business day of the preceding month.
The Nigeria Revenue Service has been directed to publish the applicable rate on its website by the third business day of every month.
The interest will be calculated as simple interest on a daily basis, running from the tax due date until payment is made.
Explaining the rationale behind the new order, Oyedele said the cost of delaying tax payments should reflect the cost to government of making up for the shortfall.
“Tax that is due belongs to the public. When it is paid late, Government may have to borrow to fill the gap, and the cost falls on everyone. This Order ties the cost of late payment to real market rates, so that delaying tax does not become a cheaper form of credit than the market itself,” he said.
The minister said the new system would also provide taxpayers with greater certainty by ensuring that the applicable rate is published regularly and applied consistently by tax authorities.
“Just as important is certainty. Every taxpayer, whether dealing with the Nigeria Revenue Service or a State revenue service, will know the rate in advance, see it published every month, and be charged in the same way. Clear rules make compliance easier and support a fair, predictable tax system,” he added
The order covers tax payments made through self-assessment, as well as assessments administered by the Nigeria Revenue Service and the State and FCT Internal Revenue Services.
The ministry said the new rates will apply to interest arising from October 1, 2026, including interest on tax liabilities that became due before that date.
However, interest that arose before October 1 will remain subject to the rules in force at the time, where specifically provided for under those rules.
The order also supersedes the 2017 notice on interest on unpaid taxes and other earlier notices on the matter.
The ministry clarified that the new order does not alter the 10 per cent penalty for late payment provided under Section 65 of the Nigeria Tax Administration Act.
It added that relevant tax authorities retained powers under Section 66 of the Act to waive penalties or interest where good cause was established.
The Federal Ministry of Finance advised taxpayers to file their returns and pay applicable taxes on time, while those with outstanding liabilities were encouraged to settle them promptly or engage the relevant tax authority.